
Adam Zeman Answers Wisconsin Home Buyers' Down Payment, FHA and HELOC Questions
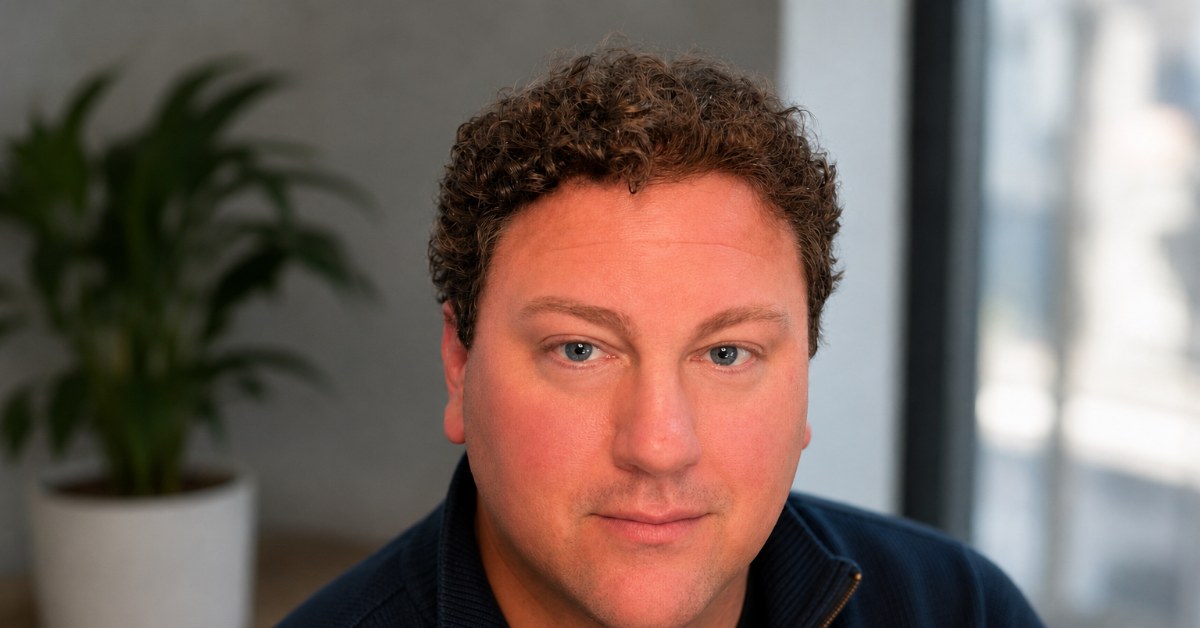
Adam Zeman : Edge Home Finance, Senior Loan Originator in Wauwatosa, Wisconsin (NMLS #870441)
The Wauwatosa loan officer explains how little buyers may need down, FHA versus conventional, and how homeowners can tap equity and keep their rate.
"Most people who call me have already talked themselves out of buying because of something they heard once, like needing 20% down or perfect credit," said Zeman. "Neither one is true. The fastest way to know where you stand is to look at your own numbers."
Do you need 20% down to buy a home in Wisconsin?
No. Conventional loans allow as little as 3% down for many first-time buyers, which is $9,000 on a $300,000 home. FHA loans allow 3.5% down with a credit score of 580 or higher, or $10,500 on the same home. VA and USDA loans can require no down payment for eligible borrowers and properties. Putting 20% down on a conventional loan avoids private mortgage insurance (PMI), but it is not required to buy.
Who counts as a first-time home buyer?
Many programs define a first-time buyer as someone who has not owned a home in the past three years, so some past owners qualify again.
What is the difference between FHA and conventional loans?
Conventional loans usually require a credit score of 620 or higher. PMI can be cancelled on request once the balance reaches 80% of the home's original value, and it ends automatically at 78%.
FHA loans allow a 580 credit score with 3.5% down, or 500 to 579 with 10% down. Borrowers pay a 1.75% upfront mortgage insurance premium, usually added to the loan, plus an annual premium that lasts for the life of the loan when the down payment is under 10%.
"FHA is often the easier approval. Conventional is often the cheaper loan over time, because the mortgage insurance can come off," Zeman said. "The right choice depends on your credit, your savings and how long you plan to stay."
What does it take to get pre-approved?
Most salaried borrowers need recent pay stubs, W-2s and bank statements, plus permission to check credit. A pre-approval shows your real price range before you shop and strengthens your offers. Most Wisconsin purchases close in about 30 to 35 days after an accepted offer.
How can homeowners use equity without giving up a low rate?
A home equity line of credit (HELOC) is a second loan that leaves the first mortgage in place. A cash-out refinance replaces the whole mortgage at a new rate.
For example, on a $400,000 home with a $250,000 mortgage, a lender that allows combined borrowing up to 85% of the home's value ($340,000) would leave room for a line of credit of up to about $90,000. Limits vary by lender, credit and income.
"If your mortgage rate is lower than what's available now, refinancing the whole balance to borrow $40,000 rarely makes sense," Zeman said. "A HELOC is often the better tool. Sometimes neither one fits, and I'll say so."
More answers
The full guides for first-time home buyers in Wisconsin, FHA loans in Wisconsin and HELOCs in Wisconsin are at adamzmortgageteam.com. Borrowers can confirm any loan officer's license for free at NMLS Consumer Access.
To talk through your own numbers, call or text Adam Zeman at (414) 975-2654.
About Adam Zeman
Adam Zeman is a Senior Loan Originator with Edge Home Finance, LLC, 11220 W Burleigh St, Suite 174, Wauwatosa, WI 53222. With 15+ years in mortgage lending, he helps buyers and homeowners across Wisconsin, including Milwaukee, Waukesha, Madison and Green Bay. He works with conventional, FHA, VA, USDA, construction, home equity and investor loans, compares options from 130+ wholesale lenders, and holds a 5.0-star rating on Google.
Adam Zeman, NMLS #870441. Edge Home Finance, LLC, NMLS #891464. Licensed in Wisconsin. Equal Housing Opportunity. Not a commitment to lend. All loans are subject to credit approval and underwriting, and not all borrowers will qualify. Examples are illustrations, not quotes or offers. Program guidelines and loan limits can change. Not affiliated with or acting on behalf of HUD, FHA, VA, USDA or the federal government.
Adam Zeman
Edge Home Finance
+1 414-975-2654
Visit us on social media:
LinkedIn
Instagram
Facebook
YouTube
Other
Legal Disclaimer:
EIN Presswire provides this news content "as is" without warranty of any kind. We do not accept any responsibility or liability for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this article. If you have any complaints or copyright issues related to this article, kindly contact the author above.
